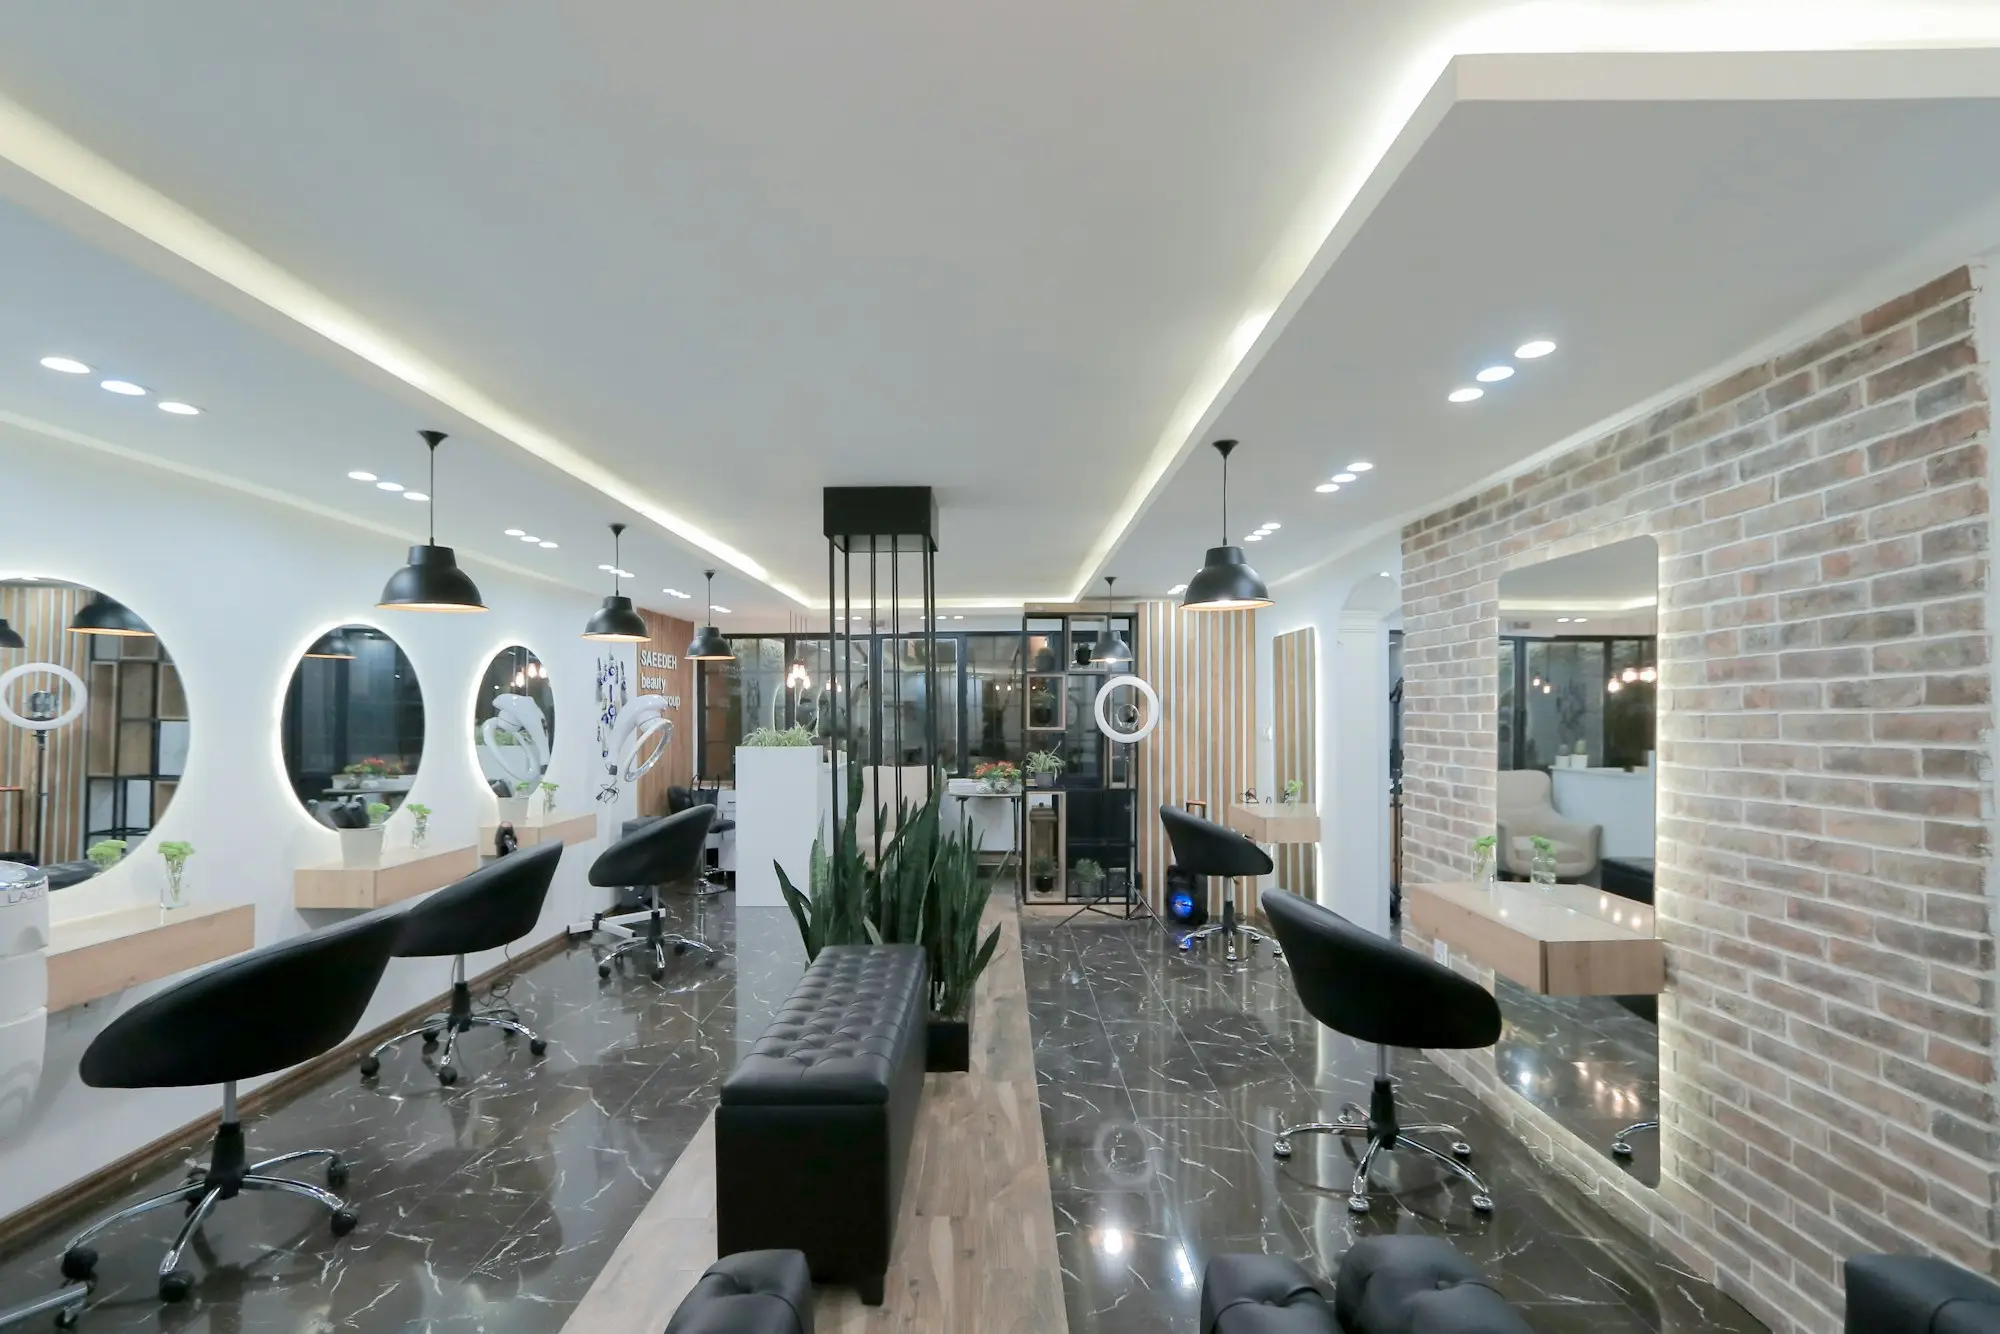
Quick answer
Business funding for salons and barbers usually covers fit-outs and refurbishments, styling chairs, basins and beauty equipment, retail product stock, quiet periods and adding new stylists or a second location. Daily card takings make trading easy for lenders to read. Unsecured funding typically runs from $5k to $500k, and equipment finance suits chairs and clinical devices.
Key points
- Fit-outs and equipment are the main investments
- Daily takings show trading clearly
- New stylists take time to build clientele
- Quiet weeks follow busy holiday periods
Hair, beauty and barber businesses depend on atmosphere and skilled people. A fresh fit-out attracts clients, good equipment improves results, and talented stylists drive repeat bookings. All three cost money before they pay back.
Where the money goes in salons and barbers
Takings arrive daily from appointments and retail product sales. Wages, rent and product orders run weekly or monthly. Busy periods before Christmas, weddings and school formals are followed by quieter weeks. Clinical beauty equipment, such as laser devices, can be a major purchase.
The usual cash flow pinch points
- Salon refurbishments and fit-outs.
- Chairs, basins and beauty or laser equipment.
- Retail product orders.
- New stylists building their client base.
- January and winter lulls.
Numbers in front of you? Put them in the enquiry and we will tell you plainly what looks realistic. Enquiring does not touch your credit file.
Funding that tends to fit
| Funding | Why it suits salons and barbers |
|---|---|
| Equipment finance | Chairs, basins and clinical beauty devices |
| Working capital loan | A refurbishment or new stylist ramp-up |
| Line of credit | Quiet weeks and product orders |
| Property-secured loan | A second salon or major fit-out |
What lenders look at
- Daily takings and booking consistency.
- Lease term remaining.
- Equipment finance in place.
- Wages relative to revenue.
Most unsecured lending in this sector falls between $5k and $500k. Owners with residential or commercial property can access $20k to $5m on a property-secured basis, with no valuation and flexible repayment structures.
Getting your file ready
Think about what an assessor sees when they open your statements. For salons and barbers, they will look for regular income, how the account copes in the leanest month and whether other lenders are already taking a slice each week. You can help by choosing a sensible time to apply, explaining seasonal swings or one-off events, and bringing tax lodgements up to date before you enquire.
A worked example (illustrative)
A barbershop with four chairs wants to refit and add two more, costing $55,000 including chairs and plumbing. Equipment finance covers the chairs and basins, and a small working capital loan funds the building works. The extra chairs are filled by two new barbers over the following months.
Ways to need less funding
Use your booking system to forecast quiet weeks, encourage rebooking before clients leave and manage retail stock tightly. Plan refurbishments for your quietest period.
The short version
- Fit-outs and equipment are the main investments
- Daily takings show trading clearly
- New stylists take time to build clientele
- Quiet weeks follow busy holiday periods
How we work through it with you
We keep it simple. Your enquiry goes to one team. That team calls you, confirms the details, asks for bank statements or property details and tells you honestly what looks achievable. If the right answer is a payment plan, a conversation with a supplier or waiting a quarter, we will say so. If funding fits, you get the amount, term, repayments and total cost spelled out before you sign anything. You will always know who is handling your file and how to reach them.
Is funding the right answer here?
Good borrowing has a job and an end date. Before you enquire, write down in one sentence what the money is for and how it will be repaid. If that sentence is easy to write, you are probably in the right place. If it is not, it is worth a closer look at the business’s cash flow before taking on new repayments.
Getting your details together
You do not need a folder of financial statements to start an enquiry. For most unsecured and property-secured funding, these few items cover the essentials:
- Photo ID for each director or owner.
- Access to your business bank account for a secure statement link.
- Your latest BAS, if it is handy.
- Details of existing finance, including any daily or weekly repayments.
- For property-secured funding, the property address and current loan balance.
About the questions we ask
Every question on the form is there for a reason: it changes which funding fits. Describe the business as it stands today rather than the version you expect in six months. Mention any default, tax debt or recent decline in the notes. We look at those situations all the time, and knowing early lets us head straight for options that can actually work.
Ready to check your options?
Ready when you are. Send your enquiry and a real person will review it and call you back. There is no credit check to enquire and no selling of your details. The only thing we ask is accuracy: tell us what you really need, what the business really turns over and how your credit really looks, so the first match is the right match.
Frequently asked questions
Can salons finance laser or clinical equipment?
Yes. Equipment finance is commonly used for clinical beauty devices, secured on the equipment.
Is funding available for a new salon?
New salons may find unsecured funding harder at first. Equipment finance and property security can help.
Will an enquiry affect my credit score?
No. An enquiry runs no credit check. A credit check only happens if you decide to go ahead with a specific offer.
Can salons and barbers with bad credit get business funding?
Often, yes. Credit marks are considered case by case, with weight on how the business trades now and any property security available. Explain the background honestly in the enquiry.
Ask right here, it takes a minute
The same 60-second enquiry, on this page. No credit check to enquire, and the person who reads it is the person who calls you.